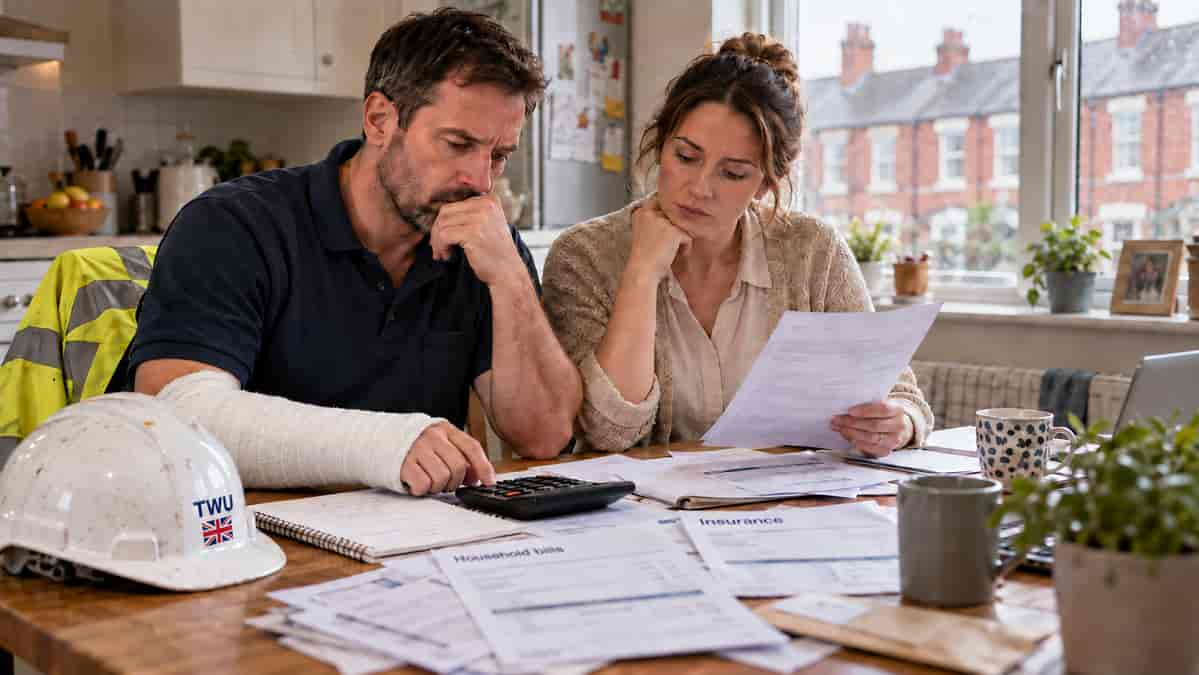
Millions of UK adults have no life insurance, critical illness cover or income protection, raising questions about how working households would cope if illness or bereavement disrupted their income.
The rent still needs paying. The food shop cannot wait. And the mortgage payment arrives whether someone is well enough to work or not.
For households dependent on regular earnings, a sudden health crisis can quickly become a financial one.
The Financial Conduct Authority says 58% of adults do not hold protection insurance, with renters, self-employed people and gig workers among those disproportionately without cover. Its new partnership programme to improve financial security, announced on 21 September 2026, aims to encourage more people to consider their needs.
That statistic requires care. It concerns specific protection products, rather than all insurance. It does not mean every uninsured adult faces financial collapse: savings, workplace benefits and other household income can provide support.
But it raises a question every working household should be able to answer: what would pay the bills if earnings stopped?
Why renters and gig workers face particular pressures
A mortgage application can prompt a discussion about insurance. Renting a home should also be an opportunity to consider how housing costs would be met during illness.
For people earning through freelance assignments, delivery work or short contracts, the calculation can be especially difficult. Income may fluctuate, while household commitments remain fixed.
Consider a self-employed worker recovering from an injury. Alongside the immediate loss of earnings, they might still face vehicle costs, rent and family expenses. This illustrative situation shows why financial resilience involves more than having work available today.
The Workers Union’s information on support for self-employed workers explores related challenges, including late payments and contractual disputes, which can place further pressure on household finances.
Employees should also understand their existing arrangements. Reviewing a contract of employment and asking an employer to explain sickness benefits can help establish where support begins and ends.
What protection insurance can do
Different policies address different risks, making clear explanations essential.
MoneyHelper’s guide to income protection insurance explains that it can replace part of someone’s income when illness or an accident prevents them working. Payments normally begin after an agreed waiting period and remain subject to policy conditions.
Critical illness cover operates differently, generally paying a lump sum following a diagnosis that meets the policy’s specified conditions. Workers should check exactly what is covered, rather than assume any serious diagnosis automatically qualifies.
The practical issue is whether available support would meet essential costs for long enough. Having some insurance does not necessarily mean every financial risk is covered.
What the FCA plans to change
The regulator’s programme brings together organisations that encounter consumers at important financial moments.
The Money and Pensions Service and the Digital Property Market Steering Group will encourage protection discussions around events such as becoming a parent, buying a property or renting a home.
The Protection Distributors’ Group will lead an awareness campaign aimed at groups less likely to hold cover. Meanwhile, the Association of Mortgage Intermediaries will work on improving how advisers explain protection options.
The FCA’s Pure Protection Market Study found that competition generally delivers good outcomes for existing policyholders. However, limited awareness and difficulties accessing products can leave others outside the market.
The response will use existing frameworks rather than broad new regulation. Engagement starts in October 2026, with actions beginning by year-end and meaningful progress expected over the following 12 to 18 months.
What UK workers can check now
A useful starting point is to establish the household’s financial position before considering any purchase.
- Understand workplace benefits. Ask what sick pay and insurance benefits apply, how long they last and whether they end when you leave.
- Calculate essential monthly costs. Include housing, food, utilities, borrowing commitments and childcare.
- Check existing resources. Consider savings, other household earnings and any cover already in place.
- Examine policy limits. Understand waiting periods, exclusions, payment amounts and how inability to work is assessed.
- Get help with individual decisions. MoneyHelper offers free information, while a specialist broker or financial adviser can explain suitable options.
Insurance is not automatically necessary for everyone. MoneyHelper notes that sufficient savings, family support or generous workplace benefits may reduce the need for income protection. Individual circumstances matter.
Affordability will determine whether this works
Clearer conversations could help workers make better-informed decisions. They cannot, by themselves, create room in an already stretched household budget.
That is the central challenge. A worker may understand the risk perfectly well and still struggle to afford another monthly payment.
The programme’s success should therefore be judged by whether people can access suitable, understandable and affordable cover, and receive the support their policy promises when they need it.
For working households, financial security must be measured in bills paid and breathing space during a crisis.